
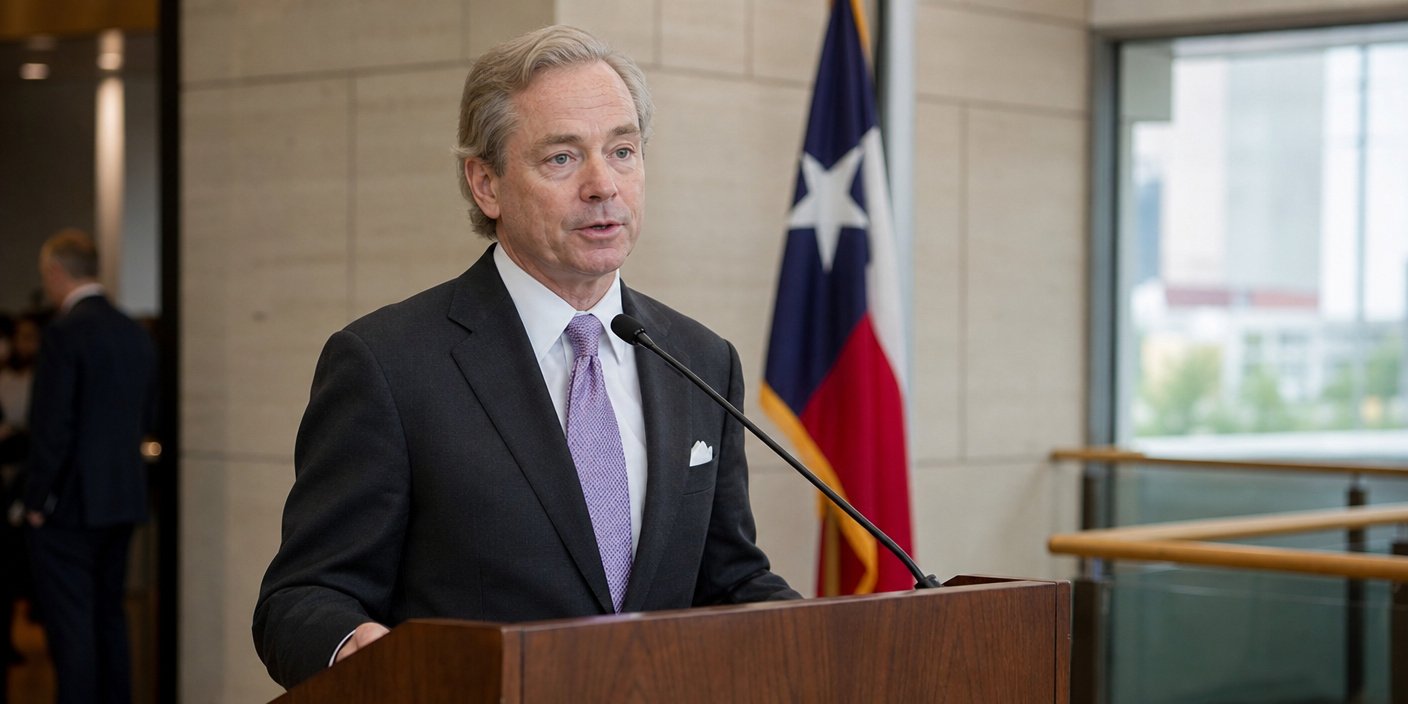
In a decisive move to bolster the state’s burgeoning digital economy, Texas Comptroller Don Huffines has officially announced a series of proposed amendments to state tax rules that would fundamentally reclassify cloud computing, internet hosting, and artificial intelligence (AI) services. Under these proposed changes, these critical pillars of the modern digital infrastructure would be designated as non-taxable under existing state data processing laws. The announcement marks a significant shift in fiscal policy, aimed directly at lowering overhead costs for businesses while simultaneously reducing the financial burden on consumers relying on digital services.
Key Highlights
- Tax Exemption Scope: The proposed rule changes would specifically exclude cloud computing, AI, and internet hosting from taxation categorized under “data processing” services.
- Economic Catalyst: The move is designed to attract tech investment to Texas by removing barriers to entry for startups and established digital corporations.
- Consumer Savings: By eliminating the tax pass-through, the Comptroller’s office anticipates a direct reduction in costs for businesses and, eventually, individual users of these services.
- Modernizing Regulations: The proposal serves as an update to outdated tax codes that often misclassify modern, scalable digital infrastructure as legacy “data processing” services.
Rethinking Digital Taxation in the Cloud Era
The landscape of the modern economy is built on a foundation of cloud architecture and artificial intelligence. However, for years, businesses in Texas—and indeed across the nation—have struggled with the ambiguity of tax codes drafted in an era of local server maintenance. When Texas tax law classifies “data processing” as a taxable service, it often ensnares modern Software-as-a-Service (SaaS) and cloud-hosting platforms in a regulatory net never intended for them. Comptroller Don Huffines’ proposal aims to sever that connection.
The Shift from Legacy Data Processing
Historically, the state of Texas has viewed “data processing” as a taxable activity. This definition has been a point of contention for years. As companies moved their operations from physical, on-premises servers to cloud-based environments, they effectively became subject to tax liabilities simply for adopting modern efficiency tools. The current proposal clarifies that the hosting of data and the running of AI algorithms do not constitute the taxable “processing” that the original legislation intended to regulate. By clarifying this distinction, the state hopes to provide much-needed legal certainty to a sector that has been plagued by audit risks and ambiguous compliance requirements.
Boosting the Texas Silicon Corridor
Texas has been aggressively courting tech giants and startups alike, with major corporations relocating their headquarters to cities like Austin, Dallas, and Houston. However, critics have long argued that the state’s tax policy regarding digital services was a hidden deterrent to long-term growth. If enacted, this proposal would provide a significant competitive advantage to Texas over neighboring states. For a business operating a massive cloud-based architecture, the removal of a sales tax on these services represents a non-trivial reduction in operating expenses—money that can be reinvested into hiring, research, and development.
Future-Proofing the Regulatory Framework
Perhaps the most forward-looking aspect of this proposal is the inclusion of Artificial Intelligence. While AI services were barely a consideration when many of these state tax statutes were written, the Comptroller’s proposal explicitly targets them as non-taxable. This is a clear signal that Texas intends to remain at the forefront of the AI revolution. By explicitly removing AI services from the tax burden, the state is creating a “safe harbor” environment. This provides the stability necessary for developers to innovate without fearing that their AI-driven software will become a liability due to complex, antiquated tax classifications.
Implementation and Expected Challenges
Transitioning to this new model will not be without its hurdles. The Comptroller’s office will likely face challenges regarding the exact demarcation between “taxable data services” and “non-taxable cloud services.” Companies that provide a hybrid of services—some traditional data processing and some cloud hosting—may need clear guidance to avoid tax audits. The industry will be closely watching the rulemaking process to ensure that the final language is as precise as the intent behind it.
FAQ: People Also Ask
Q: How will this proposal affect individual consumers?
A: While the primary impact is on business-to-business transactions, the goal is for these tax savings to reduce costs for services businesses provide to the end-user. As companies see their cloud hosting overhead drop, the expectation is that these savings will be passed down to the consumer.
Q: Does this proposal cover all types of cloud software?
A: The proposal is specifically aimed at cloud computing, internet hosting, and AI services. It clarifies these as non-taxable, separating them from traditional taxable data processing. Businesses should consult the specific administrative rules once finalized to ensure their specific SaaS products fall under these exemptions.
Q: When will these changes go into effect?
A: The proposal is currently moving through the administrative rulemaking process. Following public commentary and official review, a timeline for implementation will be set by the Comptroller’s office.
Q: Is Texas the only state considering this?
A: Many states are currently grappling with how to define cloud services in their tax codes. Texas’s move is among the most aggressive attempts to explicitly exempt these services, placing it in a strong position to attract companies that are currently scouting locations with the most favorable digital-business environments.