
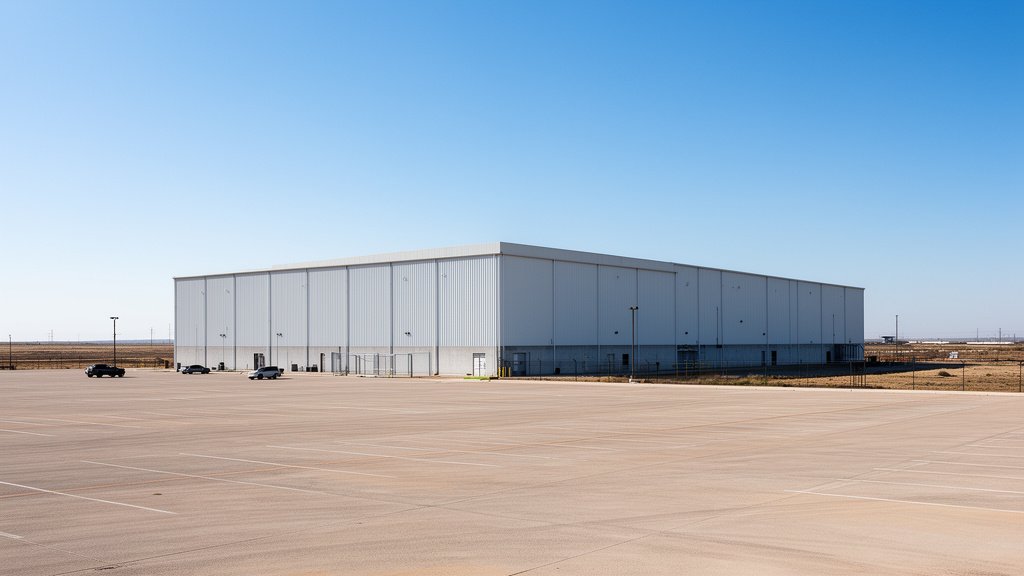
In the sprawling industrial landscape of Mesquite, Texas, a $533 million manufacturing facility stands as a stark monument to one of the most controversial chapters in state economic policy. An exhaustive investigation by WFAA and ProPublica has peeled back the curtain on this massive project, revealing a disconnect between promised economic development and the tangible output—or lack thereof—that has left taxpayers questioning the efficacy of the state’s Chapter 313 tax incentive program. While the capital investment reached the hundreds of millions, the reality of the facility’s day-to-day operations suggests a future where high-tech automation has decoupled corporate tax breaks from the local jobs they were originally designed to protect.
The Anatomy of the Incentive Scandal
The project in question, centered on a massive manufacturing investment, was touted as a cornerstone of Mesquite’s economic revival. Local officials and state administrators approved significant tax breaks under the Chapter 313 program, a Texas law designed to lure corporations by allowing them to limit the appraised value of their property for school district taxes. The premise is simple: in exchange for these massive tax breaks, companies promise to build large-scale facilities, invest in local infrastructure, and, most importantly, create high-quality, permanent jobs for the community.
However, the WFAA/ProPublica investigation highlights a critical misalignment. The $533 million figure reflects the ‘capital investment’—the cost of the facility and the expensive, highly automated machinery inside. But as the investigation notes, these investments often prioritize capital expenditure over human capital. The result is a facility that looks impressive on a balance sheet but functions as a ‘ghost’ in terms of tangible community economic stimulation. The investigative report suggests that the factory, despite its immense price tag, failed to produce the volume of manufacturing output or the permanent employment levels that were used to justify the initial tax exemptions.
The Automation Paradox and Job Creation
A central theme in the failure of this project is the role of advanced automation. Modern manufacturing is increasingly software-driven and robotic. When companies negotiate Chapter 313 deals, they often present job creation numbers based on outdated models of the manufacturing sector. The Mesquite facility serves as a case study for why this logic is failing: the technology required to build these products is so efficient that it requires only a skeleton crew of highly specialized technicians rather than the robust local workforce that local officials were promised.
This creates a ‘hollow’ economic engine. The school districts, which are the entities effectively paying the price for these tax breaks through lost revenue, do not see the influx of new residents, students, or consumer spending that would typically accompany a manufacturing boom. Instead, the facility operates with a minimal footprint, leaving the district with a significant loss in potential tax revenue and no corresponding growth in the local tax base.
Accountability in the Wake of Investigation
The fallout from this report has reignited a fierce debate in the Texas Legislature regarding the oversight of corporate welfare. Critics argue that the Chapter 313 program, which was allowed to expire but continues to impact existing agreements, lacked the ‘clawback’ provisions necessary to hold companies accountable. If a company fails to meet its job creation targets, there are often few legal mechanisms to force them to pay back the taxes they were forgiven.
For the residents of Mesquite, the story is one of missed opportunity. The $533 million valuation was used to sell the project to the public, yet the investigation shows that the project’s ‘output’—in terms of economic health for the city—was negligible. The investigative journalists argue that without rigorous auditing and performance-based incentives that evolve with the manufacturing sector, these public-private partnerships will continue to favor corporate balance sheets at the expense of public education funding and local municipal health.
Secondary Angles: Looking Beyond the Headlines
1. The Death of Chapter 313: This investigation serves as a post-mortem for the Chapter 313 program. It illustrates why policymakers allowed the program to lapse, citing it as an inefficient tool that prioritizes big business over public schools.
2. The Future of Manufacturing Policy: This case forces a reckoning on how municipalities should evaluate manufacturing incentives in an age of AI and robotics. If a factory is fully automated, should it qualify for tax breaks based on job creation? The answer appears to be a resounding ‘no’ from economic analysts.
3. Institutional Oversight: The role of local school boards in vetting these deals is under scrutiny. Often, these boards are out-negotiated by corporate legal teams, leading to lopsided agreements where the school district bears the risk while the corporation reaps the reward.